Does Insurance Cover Hail Damage to Your Roof?
Every summer, hail and prairie wind push a lot of Saskatchewan roofs into an insurance claim. This guide covers what SGI and private home policies generally pay for, where they usually stop, and how to get a hail-damaged roof documented the right way. Treat it as general information, not a stand-in for reading your own policy.
We at W Contracting Roofing handle hail claims for homeowners in Saskatoon and the surrounding towns.
- What hail and wind damage insurers generally cover
- Cosmetic marks vs claimable bruising, explained
- HAAG Certified inspections and full claim documentation
Does insurance cover hail damage to your roof?
In most cases, yes. A sudden hailstorm or a wind event that damages your roof is generally covered under SGI home policies and private insurers here in Saskatchewan.
A roof that quietly wore out over the years, or one with surface marks that do not change how it performs, usually is not. What you actually have comes down to how your own policy is written, so read it and have the roof looked at either way.
From a Google review
A hail estimate the adjuster took note of
Rob had Nathan out for a hail estimate, and the roof claim ended up combined with an earlier garage issue.
“We had Nathan from W Contracting out for a hail estimate, and the service was nothing short of remarkable. In the end, we had to combine our roof claim with a previous garage issue, but the estimate Nathan provided-along with his knowledge and advice-was so thorough that even my insurance adjuster took note. I highly recommend W Contracting for all your roofing needs!”
How hail-damage coverage works in Saskatchewan (SGI and private)
Home insurance in Saskatchewan is written either through SGI or through a private insurer, and a standard home policy generally covers sudden, accidental damage from a storm, hail and high wind included. So when a storm hits your roof out of nowhere, the repair or the replacement usually runs through a claim instead of coming out of your own pocket. Most storm-damaged roofs we see in Saskatchewan go that route.
Coverage still comes down to your policy. Two houses on the same block can sit on different deductibles and different limits, with wording that reads its own way on each one, so the only way to be sure is to check your policy or ask your broker. The one thing that holds steady across SGI and private policies is the trigger.
Insurers pay for sudden, storm-caused damage, not for a roof that quietly reached the end of its life. If yours took a hit, our roof insurance claims page walks through how we handle an SGI claim from the first call to the finished roof.
Real reviews
What our customers say
Rated 5.0 on Google · W Contracting Roofing · read them on Google
We had Nathan from W Contracting out for a hail estimate, and the service was nothing short of remarkable. In the end, we had to combine our roof claim with a previous garage issue, but the estimate Nathan provided-along with his knowledge and advice-was so thorough that even my insurance adjuster took note. I highly recommend W Contracting for all your roofing needs!
Thanks to Nathan and his team. We had a leaky roof and what we thought was going to be a total nightmare and financial disaster turned out to be a relaxing, seamless and affordable process. From the initial phone call to the end of the job Nathan kept communication going and was patient and knowledgeable when I was trying to choose the right shingles. I can’t thank Nathan and the team enough. We were so impressed we didn’t bother obtaining any quotes from other companies. It’s W Contracting all the way!!!
We were fortunate to find W contracting when we needed a roof replacement. An earlier company we contacted kept saying they'd start in a few days... and then never showed up. Nathan and his professional crew were methodical, and willing to do the little extras that a shingling job may require. They were prompt, quick, thorough and left the site very tidy. Price was good and the street appeal of our house went up, thanks to Nathan's team. A very solid 10 out of 10. We heartily recommend them with absolutely no reservations.
We had new shingles put on our home and had a very positive experience with Nathan and his crew. We would definitely recommend them. They have a great selection of shingles to choose from and a great warranty. Thank you to Nathan and the crew for treating our home well and making the roof look great.
Nathan and the crew were wonderful to deal with. From repairing the roof, installing new shingles, clean-up and competitive pricing, they were professional and efficient in every step. Would trust them to do a roof anytime and will recommend them to everyone we know.
Nathan and his team of roofers are definitely a fantastic group to work with. Nathan came out at 3 am to retarp my roof after the tarp was tore off in a storm. They did a fantastic job with all including clean up. I would fully recommend them. 5 plus stars
Nathan was fast and efficient fixing my rain gutter after it blew down during the night! Very friendly would definitely recommend.
Would recommend Nathan and his team to anyone looking for quality roof job done. They were very accommodating with my time frame, budget and nature of the job. Left the site clean and tidy. A+
What is usually covered and what is not
Insurance exists for the sudden and the accidental, not for slow decline. A roof bruised in a hailstorm, or one stripped of shingles by a hard prairie wind, is the kind of loss an SGI or private policy is meant to answer for. A roof that simply aged out, or that failed because upkeep got put off year after year, generally is not.
That distinction is the difference between filing a claim and buying a new roof yourself.
Storm damage moves you from one side of that line to the other, which is exactly why a HAAG Certified look at the roof pays off before you settle on an answer. The table below lays out the usual pattern.
Usually covered vs usually not covered
| Usually covered | Usually not covered |
|---|---|
| Sudden hail bruising that shortens the life of the roof | Gradual wear and tear from age |
| Wind-torn or lifted shingles from a storm | Cosmetic-only marks that do not affect performance |
| Storm-driven water intrusion and related interior damage | Damage from deferred maintenance or neglect |
| Related roof components damaged in the same storm event | Manufacturing defects, which are handled under warranty, not insurance |
This is the general pattern, not a verdict on your particular roof. Policies vary in their wording, and the only way to know how yours reads is to check it and have the damage inspected.
Free inspection
Not sure if your damage is a claim?
Book a free, no-obligation HAAG Certified inspection and we will tell you honestly where your roof stands.
Cosmetic vs functional (claimable) damage
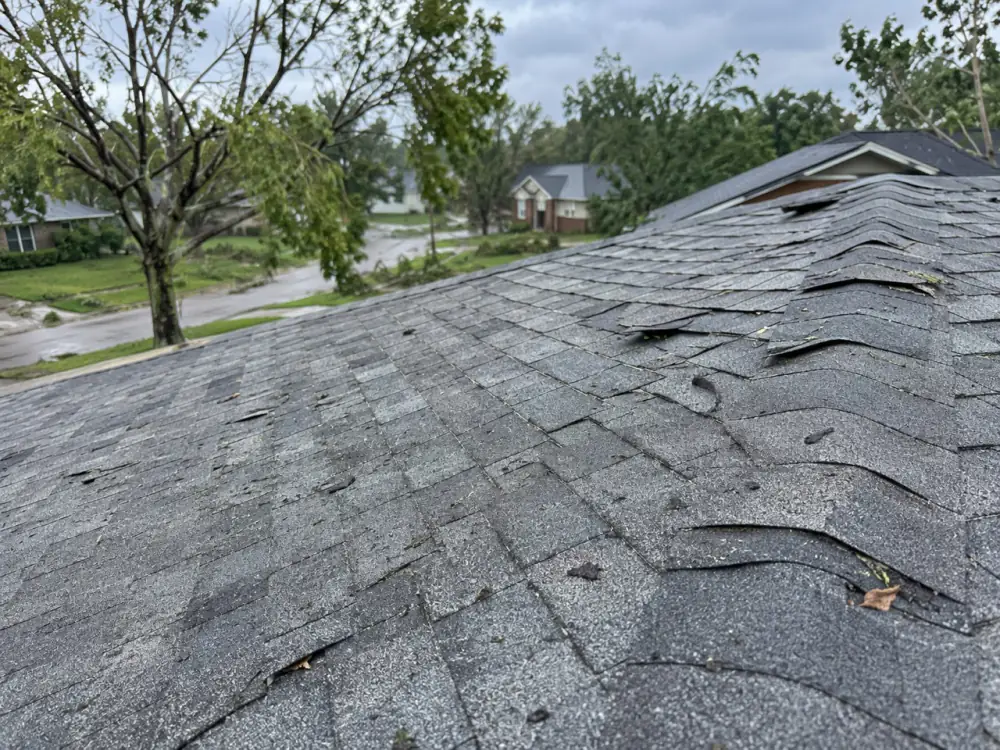
Not every mark a storm leaves is worth a claim. Insurers, and the HAAG inspection standard, split cosmetic damage off from functional damage. Cosmetic damage changes how a roof looks and nothing more.
Functional damage, the kind inspectors call bruising, is where a hailstone has fractured the mat under the granules, so the shingle starts shedding granules and gives out well before it should. That is what an SGI or private claim is actually built on.
Being HAAG Certified means we inspect a roof the way an adjuster does, so we can tell an ordinary cosmetic mark from bruising that will cut a roof’s life short. We will not push a replacement you do not need. Now and then the honest read is that your roof is fine, and that is worth hearing too.
Deductibles and how a claim is paid
When a hail claim gets approved, you are usually not paying for the whole roof. You cover your deductible, and your insurer covers the approved scope of the repair or replacement.
A deductible is just the share of a claim you have agreed to carry yourself, and that figure is set by your SGI or private policy, not by us. We do not quote it or guess at it.
What we do handle, as HAAG Certified inspectors, is making sure the approved scope matches the real, storm-caused damage, so you are not left covering something your policy was meant to. Your written roofing quote spells out the roofing side plainly, scope and all, with nothing buried in it.
Claim deadlines and why timing matters
Claims come with deadlines, and bruised shingles keep dropping granules while you wait, so sitting on it rarely does you any favours. The exact window to report a loss is set by your policy and your insurer, which is why the safe play is to report it early and get someone up on the roof. A free HAAG Certified inspection costs nothing and tells you where you actually stand.
Moving fast helps for a plainer reason too: after a big storm, the roofs documented early are the ones where the damage clearly ties back to that storm. Wait long enough and it gets harder for anyone, the adjuster included, to sort storm damage from everyday wear.
How to document damage and get it inspected
Solid documentation is what turns real damage into an approved claim. That means photos and video of the hail strikes and wind creases across the whole roof, not just the spots that jump out at you, with the storm date noted down.
We record the damage with photos and video and meet your SGI or private adjuster on site when it helps, then lay the scope out in plain terms. No inflated numbers, no games.
Real, storm-caused damage gets captured, so you are not paying out of pocket for something your policy covers. When you are ready to get going, our roof insurance claims page lays out how an SGI claim runs, from first call to finished roof.
Starting a claim
How to start a hail damage claim
Free inspection
After a storm we get up on the roof quickly, mark each hail hit and wind crease, and shoot it the way an adjuster would.
Document the damage
The real, storm-caused damage goes on record in photos and video, tied clearly to the storm that caused it.
File with your adjuster
The claim is yours to file. We work alongside your SGI or private adjuster and meet them on site when it helps.
Agreed scope
Once the adjuster signs off on the scope, we check that it matches the true damage on the roof, neither padded nor short.
Restoration and warranty
Then we restore the roof properly, leave the site clean, and stand behind the finished work with a 10-year workmanship warranty.
If your roof was hit, here is how we handle your SGI claim
You do not have to carry the roofing side of a claim by yourself. We inspect, document, sit down with your adjuster, and restore the roof once the scope is settled. The full SGI claim process is laid out on our roof insurance claims page, so you know what to expect before you ever pick up the phone.
Hail damage insurance questions
Does insurance cover hail damage to a roof in Saskatchewan?
Is cosmetic hail damage covered in Saskatchewan?
What is a deductible and how does a Saskatchewan hail claim get paid?
How long do I have to file a hail damage claim in Saskatchewan?
Do you handle the SGI or insurance paperwork in Saskatchewan?
Who stands behind the work
Certifications, accreditation and partners
GAF
As a GAF Certified contractor, we install GAF systems with the GAF Timberline HDZ shingle as our workhorse, and every install carries a 10-year workmanship warranty.
HAAG
We are HAAG Certified, so storm damage gets inspected the way an adjuster inspects it, and cosmetic marks get told apart from bruising that shortens a roof’s life.
Better Business Bureau
We are a BBB Accredited Business with an A rating, listed in Saskatoon.
Financeit
Our financing runs through Financeit, so a roof can be spread over monthly payments instead of paid all at once.
Get started
Not sure if your roof is a claim?
A free, HAAG Certified inspection gives you an honest answer, plus the documentation to back it up. No pressure and no obligation.